Waterland Accountants & Adviseurs Navigation
  • Home
  • About us
    • Why we
    • Our team
  • Services
    • Accountancy
    • Tax
    • Financial planning
    • Business advice
    • Administrative services
    • Salary & staff
    • Monitoring growth
  • Current
  • Vacancies
  • Contact
  • Home
  • About us
    • Why we
    • Our team
  • Services
    • Accountancy
    • Tax
    • Financial planning
    • Business advice
    • Administrative services
    • Salary & staff
    • Monitoring growth
  • Current
  • Vacancies
  • Contact

Current

Below you'll find a list of all posts that have been categorized as "Current"

Ziek gemeld en toch een Hyrox ontslag op staande voet

Ziek gemeld en toch een Hyrox: ontslag op staande voet

Ontslag op staande voet wegens deelname aan een zware Hyrox-wedstrijd na ziekmelding. Terecht?
Vaste vergoeding met terugwerkende kracht

Vaste vergoeding met terugwerkende kracht?

Kan de werkgever met terugwerkende kracht onbelast een goed onderbouwde onkostenvergoeding toekennen?
Toch behoud aftrek specifieke zorgkosten

Toch behoud aftrek specifieke zorgkosten?

Blijft de aftrek specifieke zorgkosten toch bestaan?
Nieuwe pseudo-eindheffing fossiele auto van de zaak

Nieuwe pseudo-eindheffing fossiele auto van de zaak

Werkgever gaat pseudo-eindheffing betalen voor fossiele auto’s van de zaak.
Nieuwe regels voor bedrijven die personeel in- of uitlenen

Nieuwe regels voor bedrijven die personeel in- of uitlenen (Wtta)

Wat worden de nieuwe toelatingsregels voor uitzendbureaus en detacheerders?
Na enkele maanden auto van de zaak uitsluitend zakelijk gaan gebruiken

Na enkele maanden auto van de zaak uitsluitend zakelijk gaan gebruiken

U krijgt in oktober een nieuwe auto van de zaak. Wat als u deze niet privé gebruikt en de vorige wel?
Prinsjesdag 2026 fiscale voorstellen per 1 januari 2028

Prinsjesdag 2026: fiscale voorstellen per 1 januari 2028

Wat zijn de belangrijkste voorstellen van het kabinet die op 1 januari 2028 moeten ingaan?
Prinsjesdag 2026 fiscale voorstellen per 1 januari 2027

Prinsjesdag 2026: fiscale voorstellen per 1 januari 2027

Wat zijn de belangrijkste voorstellen van het kabinet die op 1 januari 2027 moeten ingaan?
Thuiswerkdrempel bij wonen of werken in Duitsland

Thuiswerkdrempel bij wonen of werken in Duitsland

Als je in Duitsland woont en in Nederland werkt, mag je 34 dagen thuiswerken zonder gevolgen voor het heffingsrechten van Duitsland en Nederland. En andersom.
Een landgoed in de erf- of schenkbelasting

Een landgoed in de erf- of schenkbelasting

Hoe zit het met de waardering van landgoederen voor de schenk- en erfbelasting?
Gedifferentieerde premies WGA en Ziektewet 2027 bekend

Gedifferentieerde premies WGA en Ziektewet 2027 bekend

De gedifferentieerde premies WGA en Ziektewet gaan in 2027 omhoog.
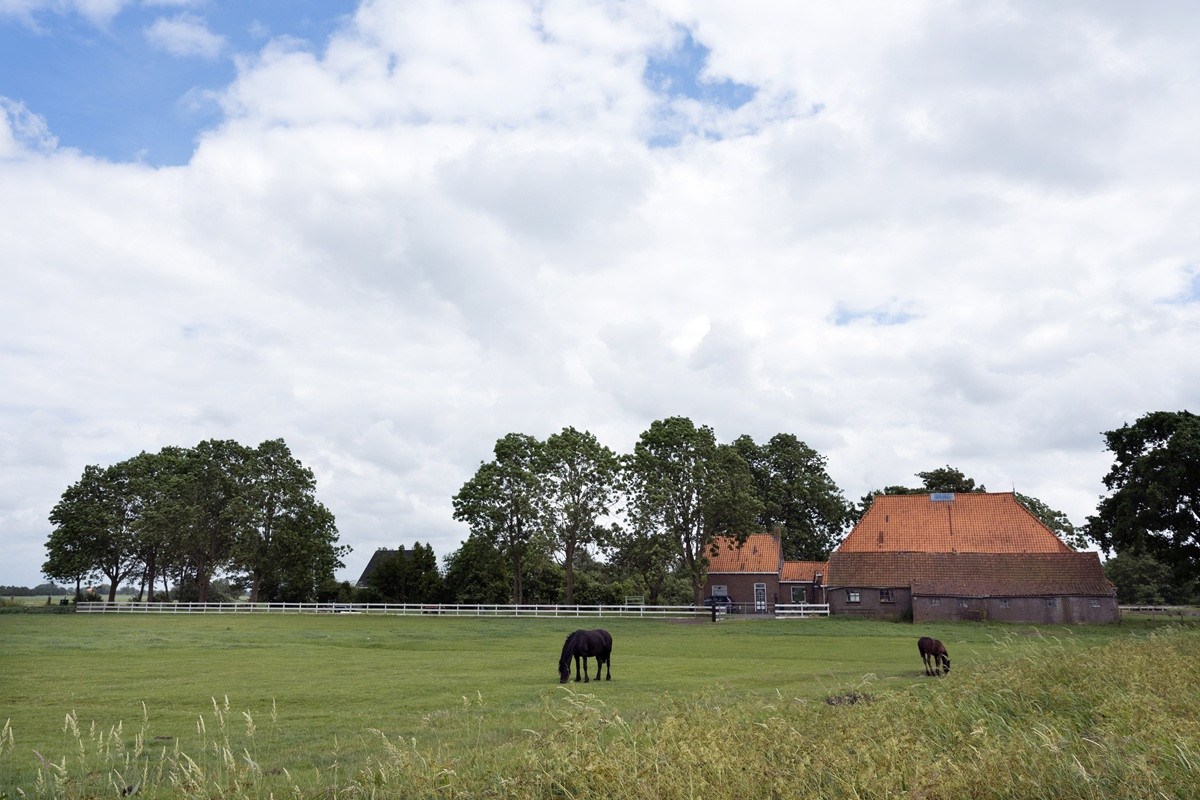
Woonboerderij met schuur, paardenbak en weiland 10,4% of 2% overdrachtsbelasting

Woonboerderij met schuur, paardenbak en weiland: 10,4% of 2% overdrachtsbelasting?

Horen de schuur, de paardenbak en een weiland bij de woning voor het 2%-tarief overdrachtsbelasting?
  • Page 2 of 20
  • ←
  • 1
  • 2
  • 3
  • ...
  • 20
  • →

Waterland Accountants Purmerend

Gorslaan 18
1441 RG Purmerend

Chamber of Commerce: 36052374
VAT: NL8066.33.153.B.01

Opening hours

Working days between 08:00 and 17:00

Contact

 0299 – 43 45 61
 info@watacc.nl

  • General terms and conditions |
  • Privacy Statement
  • | Disclaimer
  • | Complaints procedure
Waterland Accountants & Advisors
en_GBEN
nl_NLNL es_ESES en_GBEN
Waterland Accountants & Adviseurs
Management permission
To provide the best experience, we use technologies such as cookies to store and/or access information about your device. By consenting to these technologies, we may process data such as browsing behaviour or unique IDs on this site. If you do not consent or withdraw your consent, certain features and functions may be adversely affected.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service expressly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences not requested by the subscriber or user.
Statistics
Technical storage or access used exclusively for statistical purposes. Technical storage or access used solely for anonymous statistical purposes. Without subpoena, voluntary compliance by your Internet Service Provider, or additional data from a third party, information stored or retrieved solely for this purpose cannot usually be used to identify you.
Marketing
The technical storage or access is necessary to create user profiles for sending advertising, or to track the user on a site or across different sites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}